Your Local Mortgage Lender
Located in Glenview, Illinois
Personalized Mortgage Experience
Brandon Coll offers personalized service and loan options you'll love. We shop multiple lenders to find the best rate and product for you, getting you into your dream home faster.
With wholesale interest rates and cutting-edge technology, we make the mortgage process seamless. Trust the experts who focus solely on mortgages. Support your local community and experience elite client service.
Let us help you achieve your homeownership dreams!
The Home Loan Process
Mortgage Pre-Approval
Get pre-approved from one of our Loan Officers to see how much you can afford.
House Shopping
Work with a trusted Real Estate Agent to find a home you would like to move into.
Loan Application
Complete your home loan application to get the lending process started.
Don't take my word for it
Mortgage Programs
Experience the best mortgage experience located in Sterling Heights, Michigan.
Home Loan Options
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Conventional Home Loans.
FHA Home Loans.
USDA Home Loans.
VA Home Loans.
Frequently Asked Questions
How often can I refinance my mortgage?
There is no limit to the number of times you can refinance. However, you must qualify every time you apply and there will be costs associated with closing the loan each time.
Can I buy a home if I do not have money for a down payment?
Yes! There are a number of bond programs that offer low or no down payment financing options.
How do I know which mortgage is right for me?
The key to choosing the right mortgage is to understand the range of options and features available to you, as well as your budget, circumstances, and goals. Our licensed mortgage professionals are here to help you navigate that process. The more you know, the more comfortable and confident you will be choosing the best option for you and your family.
How long will the loan process take?
The Truth in Lending Act (TILA) does not permit a lender to close a loan until at least seven (7) business days have passed from the date your application was received. A typical home loan takes 30 days, as a number of third-party services such as appraisals, title work, and credit are required in conjunction with the mortgage process. Once you familiarize your Loan Officer with the details of your specific loan scenario, they will be able to provide you with a more specific timeline.
Will I qualify for a home loan?
The only way to find out is to speak with a qualified mortgage professional. Our Loan Officers have helped numerous clients who didn’t know if they could qualify to become home owners. We take the time to understand your financial situation and long-term financial goals, and then match you with the loan program that best fits your needs. Your approval for a loan may also largely depend on the price of the home you are financing. Getting pre-qualified prior to beginning your home search can give you an idea of what you may be able to afford.
Why do people refinance their mortgages?
Homeowners typically refinance to save money, either by obtaining a lower interest rate or by reducing the term of their loan. Refinancing is also a way to convert an adjustable loan to a fixed loan or to consolidate debts.
How much money will I have to pay upfront to buy a home?
This question does not have a simple, one-size-fits-all answer. The exact amount will depend on the price of the home you buy as well the type of mortgage financing you choose. Depending on your loan program, your down payment could be as much as 20% of the home’s price or as little as 3%, while some loans require no down payment at all.
Can I get a mortgage after bankruptcy?
You may still qualify for a home loan even if you have experienced a bankruptcy. The best way to find out if you qualify is to talk with a Loan Officer to discuss your options. Be sure to bring all paperwork regarding your bankruptcy so your Loan Officer can find the program that best fits your situation.
Should I lock my interest rate now, or wait until we are closer to our closing?
Interest rates fluctuate all day, every day. If an interest rate is good, it may be in your best interest to lock now. If you wait, you run the risk of an increase in rates later. If you are concerned that rates may go down after you lock, contact your Loan Officer to discuss your options. Some programs allow you to lock for an extended period and choose to lower your rate should a better one become available.
Most Recent Blog Updates
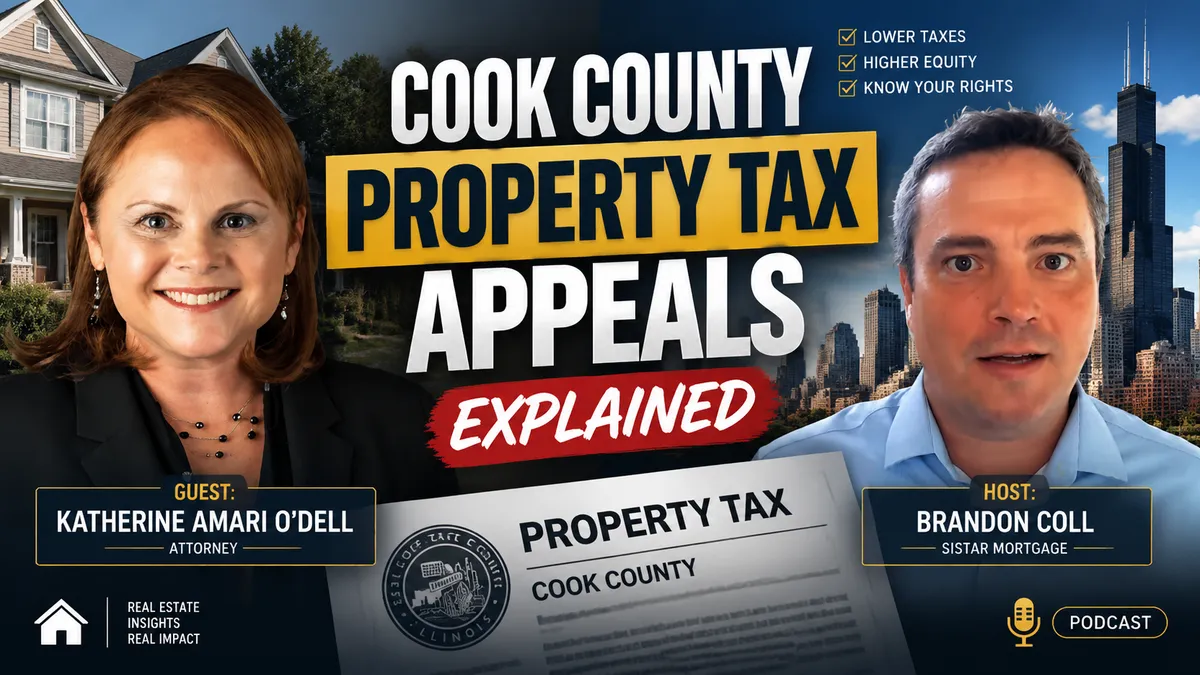
How to Appeal Your Cook County Property Taxes and What Every Homeowner Needs to Know Right Now
The Cook County Property Tax Conversation Most Homeowners Never Have
Brandon Coll at Sistar Mortgage sat down with Katherine Amari-O'Dell of Amari and Localo for a conversation that covers territory most mortgage and real estate content never touches. Cook County property tax appeals. Katherine has been doing this for over twenty-five years. Her firm does nothing else. One hundred percent real estate tax appeals inside and outside of Cook County. Before joining Amari and Localo she spent four years at the state's attorney's office. If there is a firm that understands this process at its deepest level it is this one.
How the Firm Charges and Why There Is No Financial Risk to Filing
Amari and Localo works on a contingency fee basis. No money is charged to clients unless they actually achieve a tax savings. The fee is fifteen percent of whatever savings are obtained for however many years the firm is filing.
Because Cook County's thirty-eight townships are reassessed on a rolling three-year schedule the number of years in play matters. Southern townships are being reassessed now which means a successful appeal produces three years of savings. Northern townships were reassessed in 2025 which means filing now captures two years of savings. The city of Chicago will be reassessed in 2027 which means a 2026 filing captures one year of savings.
The practical implication is clear. There is no financial downside to reaching out and exploring an appeal. If Katherine reviews the situation and does not believe there is a viable case she will say so. If a recent purchase price is above the assessor's market value she will advise against filing because disclosing that purchase price can work against the homeowner. The firm only moves forward when there is a genuine basis for a reduction.
Where to File and What the Timeline Looks Like
Cook County property tax appeals can be filed at two stages. The assessor's office opens first. The board of review opens second. Deadlines are township-specific and rolling which means there is no single universal deadline that applies to all Cook County homeowners. Each township has its own window during which appeals can be filed.
Katherine was direct about this. Check the assessor's website and the board of review's website regularly to confirm when your township is open. Call the assessor's office directly. Call your city alderman's office. Call a real estate tax attorney. There are multiple avenues for getting this information but the responsibility to track the deadline falls on the homeowner.
Her general recommendation is to file at both levels whenever possible. The assessor tends to defend his assessments more firmly and the success rate is lower on reassessment years. The board of review is more consistently willing to grant reductions for residential homeowners. Filing at both stages maximizes the opportunity.
How Appeals Are Actually Argued
For standard residential properties there are three approaches that can support a reduction.
Comparable properties from the assessor's internal database that pay lower taxes than the subject property based on similar neighborhood classification, building square footage, and age. The assessor and board of review conduct their own analysis alongside the submitted comparables and render a decision.
Recent purchase price when the purchase occurred within three years and the price is lower than the assessor's market value. This is one of the cleaner arguments available and can be highly effective when the documentation supports it.
An appraisal when comparables are not strong enough to build a compelling case. If a homeowner has an existing appraisal from a refinance that came in below the assessed value that may be usable as evidence. If no appraisal exists and the potential savings justify the cost Katherine may recommend commissioning one from a partnered appraisal company.
Exemptions That Are Being Missed and Free Money Being Left on the Table
Missed exemptions are a consistent problem across Cook County and Katherine identified several that homeowners should review immediately.
The homeowner's exemption applies to any property that is a primary residence as of January first of the tax year. It is the most basic exemption available and it rolls over automatically once applied. If it was missed for prior years a retroactive application can recover partial refunds going back to 2021. That window is closing and 2021 will likely stop being accessible around the end of the year.
The senior exemption applies to homeowners who are sixty-five or older and use the property as their primary residence. It provides a meaningful reduction.
The senior freeze is the most financially significant exemption available to qualifying seniors. Homeowners over sixty-five who have household income below sixty-five thousand dollars and live in the property as their primary residence can apply to freeze their assessed value at the prior year's level. Every year of appreciation after the freeze is locked in produces additional savings relative to what the homeowner would have paid without it. The senior freeze must be renewed annually in the spring. Missing a year means losing it.
Additional exemptions exist for veterans, disabled persons, and long-term occupancy for homeowners who have lived in the property for over ten years and meet specific assessed value parameters. The assessor's office typically notifies qualifying homeowners about the long-term occupancy exemption.
To check for missing exemptions visit the assessor's office, fill out an application, bring a copy of your driver's license as proof of residency, and submit. A corrected tax bill reflecting the exemption may be issued in the current year. Retroactive applications can recover up to five years of missed savings with 2021 representing the current cutoff that is closing soon.
What to Do Right Now
If you own property in Cook County and have not checked your exemptions recently do it now before the 2021 window closes. If you have not looked at whether your assessed value is defensible relative to comparable properties in your neighborhood that conversation with a real estate tax attorney costs nothing to explore under a contingency arrangement.
Reach Katherine Amari-O'Dell at Amari and Localo at 224-278-7937 for any questions about Cook County property tax appeals or exemption applications.
Brandon Coll at Sistar Mortgage works with homeowners and buyers across the Chicago area. Reach out to Brandon for mortgage questions including strategies for managing housing costs as part of a broader financial picture.
Sources
CookCountyAssessor.com
CookCountyBoardofReview.com
IllinoisRevenueGov
ConsumerFinancialProtectionBureau.gov
Investopedia.com

Mortgage Calculator
See your total mortgage payments using the tool below.
| Year | Interest | Principal | Balance |
|---|

Social Media Links
YouTube
